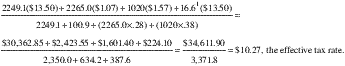Site Feedback

Title 27

Displaying title 27, up to date as of 10/15/2026. Title 27 was last amended 9/25/2026.
eCFR Content

The Code of Federal Regulations (CFR) is the official legal print publication containing the codification of the general and permanent rules published in the Federal Register by the departments and agencies of the Federal Government. The Electronic Code of Federal Regulations (eCFR) is a continuously updated online version of the CFR. It is not an official legal edition of the CFR.

Learn more about the eCFR, its status, and the editorial process.

Distilled Spirits

§ 27.40 Distilled spirits.

(a) A tax is imposed on all distilled spirits in customs bonded warehouses or imported into the United States at the rate prescribed by 26 U.S.C. 5001 on each proof gallon and a proportionate tax at a like rate on all fractional parts of each proof gallon. All products of distillation, by whatever name known, which contain distilled spirits, are considered to be distilled spirits and are taxed as such. The tax will be determined at the time of importation, or, if transferred to the bonded premises of a distilled spirits plant, at the time of withdrawal therefrom.

(b) A credit against the tax imposed on distilled spirits by 26 U.S.C. 5001 is allowable under 26 U.S.C. 5010 on each proof gallon of alcohol derived from eligible wine or from eligible flavors which do not exceed 21⁄2 percent of the finished product on a proof gallon basis. The credit is allowable at the time the tax is payable as if it constituted a reduction in the rate of tax.

(c) Where credit against the tax is desired, the person liable for the tax shall establish an effective tax rate in accordance with § 27.41. The effective tax rate established will be applied to each entry.

(Approved by the Office of Management and Budget under control number 1512-0352)

[T.D. ATF-297, 55 FR 18069, Apr. 30, 1990, as amended by T.D TTB-146, 82 FR 1134, Jan. 4, 2017]

§ 27.41 Computation of effective tax rate.

(a) The proprietor shall compute the effective tax rate for distilled spirits containing eligible wine or eligible flavors as the ratio of the numerator and denominator as follows:

(1) The numerator will be the sum of:

(i) The proof gallons of all distilled spirits used in the product (exclusive of distilled spirits derived from eligible flavors), multiplied by the tax rate prescribed by 26 U.S.C. 5001;

(ii) The wine gallons of each eligible wine used in the product, multiplied by the tax rate prescribed by 26 U.S.C. 5041(b)(1), (2), or (3), as applicable; and

(iii) The proof gallons of all distilled spirits derived from eligible flavors used in the product, multiplied by the tax rate prescribed by 26 U.S.C. 5001, but only to the extent that such distilled spirits exceed 21⁄2% of the denominator prescribed in paragraph (a)(2) of this section.

(2) The denominator will be the sum of:

(i) The proof gallons of all distilled spirits used in the product, including distilled spirits derived from eligible flavors; and

(ii) The wine gallons of each eligible wine used in the product, multiplied by twice the percentage of alcohol by volume of each, divided by 100.

(b) In determining the effective tax rate, quantities of distilled spirits, eligible wine, and eligible flavors will be expressed to the nearest tenth of a proof gallon. The effective tax rate may be rounded to as many decimal places as the proprietor deems appropriate, provided that, such rate is expressed no less exactly than the rate rounded to the nearest whole cent, and the effective tax rates for all products will be consistently expressed to the same number of decimal places. In such case, if the number is less than five it will be dropped; if it is five or over, a unit will be added.

(c) The following is an example of the use of the formula.

Batch Record

Distilled spirits 2249.1 proof gallons.
Eligible wine (14% alcohol by volume) 2265.0 wine gallons.
Eligible wine (19% alcohol by volume) 1020.0 wine gallons.
Eligible flavors 100.9 proof gallons.

(Approved by the Office of Management and Budget under control number 1512-0352)

[T.D. ATF-297, 55 FR 18069, Apr. 30, 1990, as amended by T.D. ATF-307, 55 FR 52742, Dec. 21, 1990. Redesignated by T.D. ATF-474, 67 FR 11232, Mar. 13, 2002]