Site Feedback

Title 26

Displaying title 26, up to date as of 9/10/2026. Title 26 was last amended 9/08/2026.
eCFR Content

The Code of Federal Regulations (CFR) is the official legal print publication containing the codification of the general and permanent rules published in the Federal Register by the departments and agencies of the Federal Government. The Electronic Code of Federal Regulations (eCFR) is a continuously updated online version of the CFR. It is not an official legal edition of the CFR.

Learn more about the eCFR, its status, and the editorial process.

General Rules for Determining Capital Gains and Losses

§ 1.1221-1 Meaning of terms.

(a) The term capital assets includes all classes of property not specifically excluded by section 1221. In determining whether property is a capital asset, the period for which held is immaterial.

(b) Property used in the trade or business of a taxpayer of a character which is subject to the allowance for depreciation provided in section 167 and real property used in the trade or business of a taxpayer is excluded from the term capital assets. Gains and losses from the sale or exchange of such property are not treated as gains and losses from the sale or exchange of capital assets, except to the extent provided in section 1231. See § 1.1231-1. Property held for the production of income, but not used in a trade or business of the taxpayer, is not excluded from the term capital assets even though depreciation may have been allowed with respect to such property under section 23(l) of the Internal Revenue Code of 1939 before its amendment by section 121(c) of the Revenue Act of 1942 (56 Stat. 819). However, gain or loss upon the sale or exchange of land held by a taxpayer primarily for sale to customers in the ordinary course of his business, as in the case of a dealer in real estate, is not subject to the provisions of subchapter P (section 1201 and following), chapter 1 of the Code.

(c)

(1) A copyright, a literary, musical, or artistic composition, and similar property are excluded from the term capital assets if held by a taxpayer whose personal efforts created such property, or if held by a taxpayer in whose hands the basis of such property is determined, for purposes of determining gain from a sale or exchange, in whole or in part by reference to the basis of such property in the hands of a taxpayer whose personal efforts created such property. For purposes of this subparagraph, the phrase similar property includes for example, such property as a theatrical production, a radio program, a newspaper cartoon strip, or any other property eligible for copyright protection (whether under statute or common law), but does not include a patent or an invention, or a design which may be protected only under the patent law and not under the copyright law.

(2) In the case of sales and other dispositions occurring after July 25, 1969, a letter, a memorandum, or similar property is excluded from the term capital asset if held by

(i) a taxpayer whose personal efforts created such property,

(ii) a taxpayer for whom such property was prepared or produced, or

(iii) a taxpayer in whose hands the basis of such property is determined, for purposes of determining gain from a sale or exchange, in whole or in part by reference to the basis of such property in the hands of a taxpayer described in subdivision (i) or (ii) of this subparagraph. In the case of a collection of letters, memorandums, or similar property held by a person who is a taxpayer described in subdivision (i), (ii), or (iii) of this subparagraph as to some of such letters, memorandums, or similar property but not as to others, this subparagraph shall apply only to those letters, memorandums, or similar property as to which such person is a taxpayer described in such subdivision. For purposes of this subparagraph, the phrase similar property includes, for example, such property as a draft of a speech, a manuscript, a research paper, an oral recording of any type, a transcript of an oral recording, a transcript of an oral interview or of dictation, a personal or business diary, a log or journal, a corporate archive, including a corporate charter, office correspondence, a financial record, a drawing, a photograph, or a dispatch. A letter, memorandum, or property similar to a letter or memorandum, addressed to a taxpayer shall be considered as prepared or produced for him. This subparagraph does not apply to property, such as a corporate archive, office correspondence, or a financial record, sold or disposed of as part of a going business if such property has no significant value separate and apart from its relation to and use in such business; it also does not apply to any property to which subparagraph (1) of this paragraph applies (i.e., property to which section 1221(3) applied before its amendment by section 514(a) of the Tax Reform Act of 1969 (83 Stat. 643)).

(3) For purposes of this paragraph, in general, property is created in whole or in part by the personal efforts of a taxpayer if such taxpayer performs literary, theatrical, musical, artistic, or other creative or productive work which affirmatively contributes to the creation of the property, or if such taxpayer directs and guides others in the performance of such work. A taxpayer, such as corporate executive, who merely has administrative control of writers, actors, artists, or personnel and who does not substantially engage in the direction and guidance of such persons in the performance of their work, does not create property by his personal efforts. However, for purposes of subparagraph (2) of this paragraph, a letter or memorandum, or property similar to a letter or memorandum, which is prepared by personnel who are under the administrative control of a taxpayer, such as a corporate executive, shall be deemed to have been prepared or produced for him whether or not such letter, memorandum, or similar property is reviewed by him.

(4) For the application of section 1231 to the sale or exchange of property to which this paragraph applies, see § 1.1231-1. For the application of section 170 to the charitable contribution of property to which this paragraph applies, see section 170(e) and the regulations thereunder.

(d) Section 1221(4) excludes from the definition of capital asset accounts or notes receivable acquired in the ordinary course of trade or business for services rendered or from the sale of stock in trade or inventory or property held for sale to customers in the ordinary course of trade or business. Thus, if a taxpayer acquires a note receivable for services rendered, reports the fair market value of the note as income, and later sells the note for less than the amount previously reported, the loss is an ordinary loss. On the other hand, if the taxpayer later sells the note for more than the amount originally reported, the excess is treated as ordinary income.

(e) Obligations of the United States or any of its possessions, or of a State or Territory, or any political subdivision thereof, or of the District of Columbia, issued on or after March 1, 1941, on a discount basis and payable without interest at a fixed maturity date not exceeding one year from the date of issue, are excluded from the term capital assets. An obligation may be issued on a discount basis even though the price paid exceeds the face amount. Thus, although the Second Liberty Bond Act (31 U.S.C. 754) provides that United States Treasury bills shall be issued on a discount basis, the issuing price paid for a particular bill may, by reason of competitive bidding, actually exceed the face amount of the bill. Since the obligations of the type described in this paragraph are excluded from the term capital assets, gains or losses from the sale or exchange of such obligations are not subject to the limitations provided in such subchapter P. It is, therefore, not necessary for a taxpayer (other than a life insurance company taxable under part I (section 801 and following), subchapter L, chapter 1 of the Code, as amended by the Life Insurance Company Tax Act of 1955 (70 Stat. 36), and, in the case of taxable years beginning before January 1, 1955, subject to taxation only on interest, dividends, and rents) to segregate the original discount accrued and the gain or loss realized upon the sale or other disposition of any such obligation. See section 454(b) with respect to the original discount accrued. The provisions of this paragraph may be illustrated by the following examples:

Example 1. A (not a life insurance company) buys a $100,000, 90-day Treasury bill upon issuance for $99,998. As of the close of the forty-fifth day of the life of such bill, he sells it to B (not a life insurance company) for $99,999.50. The entire net gain to A of $1.50 may be taken into account as a single item of income, without allocating $1 to interest and $0.50 to gain. If B holds the bill until maturity his net gain of $0.50 may similarly be taken into account as a single item of income, without allocating $1 to interest and $0.50 to loss.

Example 2. The facts in this example are the same as in example (1) except that the selling price to B is $99,998.50. The net gain to A of $0.50 may be taken into account without allocating $1 to interest and $0.50 to loss, and, similarly, if B holds the bill until maturity his entire net gain of $1.50 may be taken into account as a single item of income without allocating $1 to interest and $0.50 to gain.

[T.D. 6500, 25 FR 12003, Nov. 26, 1960, as amended by T.D. 7369, 40 FR 29840, July 16, 1975]

§ 1.1221-2 Hedging transactions.

(a) Treatment of hedging transactions

(1) In general. This section governs the treatment of hedging transactions under section 1221(a)(7). Except as provided in paragraph (g)(2) of this section, the term capital asset does not include property that is part of a hedging transaction (as defined in paragraph (b) of this section).

(2) Short sales and options. This section also governs the character of gain or loss from a short sale or option that is part of a hedging transaction. Except as provided in paragraph (g)(2) of this section, gain or loss on a short sale or option that is part of a hedging transaction (as defined in paragraph (b) of this section) is ordinary income or loss.

(3) Exclusivity. If a transaction is not a hedging transaction as defined in paragraph (b) of this section, gain or loss from the transaction is not made ordinary on the grounds that property involved in the transaction is a surrogate for a noncapital asset, that the transaction serves as insurance against a business risk, that the transaction serves a hedging function, or that the transaction serves a similar function or purpose.

(4) Coordination with section 988. This section does not apply to determine the character of gain or loss realized on a section 988 transaction as defined in section 988(c)(1) or realized with respect to any qualified fund as defined in section 988(c)(1)(E)(iii).

(b) Hedging transaction defined. Section 1221(b)(2)(A) provides that a hedging transaction is any transaction that a taxpayer enters into in the normal course of the taxpayer's trade or business primarily—

(1) To manage risk of price changes or currency fluctuations with respect to ordinary property (as defined in paragraph (c)(2) of this section) that is held or to be held by the taxpayer;

(2) To manage risk of interest rate or price changes or currency fluctuations with respect to borrowings made or to be made, or ordinary obligations incurred or to be incurred, by the taxpayer; or

(3) To manage such other risks as the Secretary may prescribe in regulations (see paragraph (d)(6) of this section).

(c) General rules

(1) Normal course. Solely for purposes of paragraph (b) of this section, if a transaction is entered into in furtherance of a taxpayer's trade or business, the transaction is entered into in the normal course of the taxpayer's trade or business. This rule includes managing risks relating to the expansion of an existing business or the acquisition of a new trade or business.

(2) Ordinary property and obligations. Property is ordinary property to a taxpayer only if a sale or exchange of the property by the taxpayer could not produce capital gain or loss under any circumstances. Thus, for example, property used in a trade or business within the meaning of section 1231(b) (determined without regard to the holding period specified in that section) is not ordinary property. An obligation is an ordinary obligation if performance or termination of the obligation by the taxpayer could not produce capital gain or loss. For purposes of this paragraph (c)(2), the term termination has the same meaning as it does in section 1234A.

(3) Hedging an aggregate risk. The term hedging transaction includes a transaction that manages an aggregate risk of interest rate changes, price changes, and/or currency fluctuations only if all of the risk, or all but a de minimis amount of the risk, is with respect to ordinary property, ordinary obligations, or borrowings.

(4) Managing risk

(i) In general. Whether a transaction manages a taxpayer's risk is determined based on all of the facts and circumstances surrounding the taxpayer's business and the transaction. Whether a transaction manages a taxpayer's risk may be determined on a business unit by business unit basis (for example by treating particular groups of activities, including the assets and liabilities attributable to those activities, as separate business units), provided that the business unit is within a single entity or consolidated return group that adopts the single-entity approach. A taxpayer's hedging strategies and policies as reflected in the taxpayer's minutes or other records are evidence of whether particular transactions were entered into primarily to manage the taxpayer's risk.

(ii) Limitation of risk management transactions to those specifically described. Except as otherwise determined by published guidance or by private letter ruling, a transaction that is not treated as a hedging transaction under paragraph (d) does not manage risk. Moreover, a transaction undertaken for speculative purposes will not be treated as a hedging transaction.

(d) Transactions that manage risk

(1) Risk reduction transactions

(i) In general. A transaction that is entered into to reduce a taxpayer's risk, manages a taxpayer's risk.

(ii) Micro and macro hedges

(A) In general. A taxpayer generally has risk of a particular type only if it is at risk when all of its operations are considered. Nonetheless, a hedge of a particular asset or liability generally will be respected as reducing risk if it reduces the risk attributable to the asset or liability and if it is reasonably expected to reduce the overall risk of the taxpayer's operations. If a taxpayer hedges particular assets or liabilities, or groups of assets or liabilities, and the hedges are undertaken as part of a program that, as a whole, is reasonably expected to reduce the overall risk of the taxpayer's operations, the taxpayer generally does not have to demonstrate that each hedge that was entered into pursuant to the program reduces its overall risk.

(B) Example. The following example illustrates the rules stated in paragraph (d)(1)(ii)(A) of this section:

Example. Corporation X manages its business operations by treating particular groups of activities, including the assets and liabilities attributable to those assets, as separate business units. A separate set of books and records is maintained with respect to the activities, assets and liabilities of separate business unit y. As part of a risk management program that Corporation X reasonably expects to reduce the overall risks of its business operations, Corporation X enters into hedges to reduce the risks of separate business unit y. Corporation X may demonstrate that the hedges reduce risk by taking into account only the activities, assets and liabilities of business unit y.

(iii) Written options. A written option may reduce risk. For example, in appropriate circumstances, a written call option with respect to assets held by a taxpayer or a written put option with respect to assets to be acquired by a taxpayer may be a hedging transaction. See also paragraph (d)(3) of this section.

(iv) Fixed-to-floating price hedges. Under the principles of paragraph (d)(1)(ii)(A) of this section, a transaction that economically converts a price from a fixed price to a floating price may reduce risk. For example, a taxpayer with a fixed cost for its inventory may be at risk if the price at which the inventory can be sold varies with a particular factor. Thus, for such a taxpayer a transaction that converts its fixed price to a floating price may be a hedging transaction.

(2) Interest rate conversions. A transaction that economically converts an interest rate from a fixed rate to a floating rate or that converts an interest rate from a floating rate to a fixed rate manages risk.

(3) Transactions that counteract hedging transactions. If a transaction is entered into primarily to offset all or any part of the risk management effected by one or more hedging transactions, the transaction is a hedging transaction. For example, if a written option is used to reduce or eliminate the risk reduction obtained from another position such as a purchased option, then it may be a hedging transaction.

(4) Recycling. A taxpayer may enter into a hedging transaction by using a position that was a hedge of one asset or liability as a hedge of another asset or liability (recycling).

(5) Transactions not entered into primarily to manage risk

(i) Rule. Except as otherwise determined in published guidance or private letter ruling, the purchase or sale of a debt instrument, an equity security, or an annuity contract is not a hedging transaction even if the transaction limits or reduces the taxpayer's risk with respect to ordinary property, borrowings, or ordinary obligations. In addition, the Commissioner may determine in published guidance that other transactions are not hedging transactions.

(ii) Examples. The following examples illustrate the rule stated in paragraph (d)(5)(i) of this section:

Example 1. Taxpayer borrows money and agrees to pay a floating rate of interest. Taxpayer purchases debt instruments that bear a comparable floating rate. Although taxpayer's interest rate risk from the floating rate borrowing may be reduced by the purchase of the debt instruments, the acquisition of the debt instruments is not a hedging transaction, because the transaction is not entered into primarily to manage the taxpayer's risk.

Example 2. Taxpayer undertakes obligations to pay compensation in the future. The amount of the future compensation payments is adjusted as if amounts were invested in a specified mutual fund and were increased or decreased by the earnings, gains and losses that would result from such an investment. Taxpayer invests funds in the shares of the mutual fund. Although the investment in shares of the mutual fund reduces the taxpayer's risk of fluctuation in the amount of its obligation to employees, the investment was not made primarily to manage the taxpayer's risk. Accordingly, the transaction is not a hedging transaction.

Example 3. Taxpayer provides a nonqualified retirement plan for employees that is structured like a defined contribution plan. Based on a schedule that takes into account an employee's monthly salary and years of service with the taxpayer, the taxpayer makes monthly credits to an account for each employee. Each employee may designate that the account will be treated as if it were used to pay premiums on a variable annuity contract issued by the M insurance company with a value that reflects a specified investment option. M offers a number of investment options for its variable annuity contracts. Taxpayer invests funds in M company variable annuity contracts that parallel the investment options selected by the employees. The investment is not made primarily to manage the taxpayer's risk and is not a hedging transaction.

(6) Hedges of other risks. The Commissioner may, by published guidance, determine that hedging transactions include transactions entered into to manage risks other than interest rate or price changes, or currency fluctuations.

(7) Miscellaneous provision

(i) Extent of risk management. A taxpayer may hedge all or any portion of its risk for all or any part of the period during which it is exposed to the risk.

(ii) Number of transactions. The fact that a taxpayer frequently enters into and terminates positions (even if done on a daily or more frequent basis) is not relevant to whether these transactions are hedging transactions. Thus, for example, a taxpayer hedging the risk associated with an asset or liability may frequently establish and terminate positions that hedge that risk, depending on the extent the taxpayer wishes to be hedged. Similarly, if a taxpayer maintains its level of risk exposure by entering into and terminating a large number of transactions in a single day, its transactions may nonetheless qualify as hedging transactions.

(e) Hedging by members of a consolidated group

(1) General rule: single-entity approach. For purposes of this section, the risk of one member of a consolidated group is treated as the risk of the other members as if all of the members of the group were divisions of a single corporation. For example, if any member of a consolidated group hedges the risk of another member of the group by entering into a transaction with a third party, that transaction may potentially qualify as a hedging transaction. Conversely, intercompany transactions are not hedging transactions because, when considered as transactions between divisions of a single corporation, they do not manage the risk of that single corporation.

(2) Separate-entity election. In lieu of the single-entity approach specified in paragraph (e)(1) of this section, a consolidated group may elect separate-entity treatment of its hedging transactions. If a group makes this separate-entity election, the following rules apply:

(i) Risk of one member not risk of other members. Notwithstanding paragraph (e)(1) of this section, the risk of one member is not treated as the risk of other members.

(ii) Intercompany transactions. An intercompany transaction is a hedging transaction (an intercompany hedging transaction) with respect to a member of a consolidated group if and only if it meets the following requirements—

(A) The position of the member in the intercompany transaction would qualify as a hedging transaction with respect to the member (taking into account paragraph (e)(2)(i) of this section) if the member had entered into the transaction with an unrelated party; and

(B) The position of the other member (the marking member) in the transaction is marked to market under the marking member's method of accounting.

(iii) Treatment of intercompany hedging transactions. An intercompany hedging transaction (that is, a transaction that meets the requirements of paragraphs (e)(2)(ii)(A) and (B) of this section) is subject to the following rules—

(A) The character and timing rules of § 1.1502-13 do not apply to the income, deduction, gain, or loss from the intercompany hedging transaction; and

(B) Except as provided in paragraph (g)(3) of this section, the character of the marking member's gain or loss from the transaction is ordinary.

(iv) Making and revoking the election. Unless the Commissioner otherwise prescribes, the election described in paragraph (e)(2) of this section must be made in a separate statement that provides, “[INSERT NAME AND EMPLOYER IDENTIFICATION NUMBER OF COMMON PARENT] HEREBY ELECTS THE APPLICATION OF § 1.1221-2(e)(2) (THE SEPARATE-ENTITY APPROACH).” The statement must also indicate the date as of which the election is to be effective. The election must be filed by including the statement on or with the consolidated group's income tax return for the taxable year that includes the first date for which the election is to apply. The election applies to all transactions entered into on or after the date so indicated. The election may only be revoked with the consent of the Commissioner.

(3) Definitions. For definitions of consolidated group, divisions of a single corporation, group, intercompany transactions, and member, see section 1502 and the regulations thereunder.

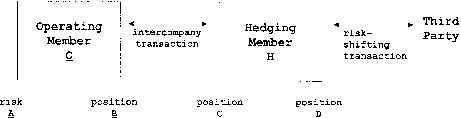
(4) Examples. General Facts. In these examples, O and H are members of the same consolidated group. O's business operations give rise to interest rate risk “A,” which O wishes to hedge. O enters into an intercompany transaction with H that transfers the risk to H. O's position in the intercompany transaction is “B,” and H's position in the transaction is “C.H enters into position “D” with a third party to reduce the interest rate risk it has with respect to its position C. D would be a hedging transaction with respect to risk A if O's risk A were H's risk. The following examples illustrate this paragraph (e):

Example 1. Single-entity treatment.

(i) General rule. Under paragraph (e)(1) of this section, O's risk A is treated as H's risk, and therefore D is a hedging transaction with respect to risk A. Thus, the character of D is determined under the rules of this section, and the income, deduction, gain, or loss from D must be accounted for under a method of accounting that satisfies § 1.446-4. The intercompany transaction B-C is not a hedging transaction and is taken into account under § 1.1502-13.

(ii) Identification. D must be identified as a hedging transaction under paragraph (f)(1) of this section, and A must be identified as the hedged item under paragraph (f)(2) of this section. Under paragraph (f)(5) of this section, the identification of A as the hedged item can be accomplished by identifying the positions in the intercompany transaction as hedges or hedged items, as appropriate. Thus, substantially contemporaneous with entering into D, H may identify C as the hedged item and O may identify B as a hedge and A as the hedged item.

Example 2. Separate-entity election; counterparty that does not mark to market.

In addition to the General Facts stated above, assume that the group makes a separate-entity election under paragraph (e)(2) of this section. If H does not mark C to market under its method of accounting, then B is not a hedging transaction, and the B-C intercompany transaction is taken into account under the rules of section 1502. D is not a hedging transaction with respect to A, but D may be a hedging transaction with respect to C if C is ordinary property or an ordinary obligation and if the other requirements of paragraph (b) of this section are met. If D is not part of a hedging transaction, then D may be part of a straddle for purposes of section 1092.

Example 3. Separate-entity election; counterparty that marks to market. The facts are the same as in Example 2 above, except that H marks C to market under its method of accounting. Also assume that B would be a hedging transaction with respect to risk A if O had entered into that transaction with an unrelated party. Thus, for O, the B-C transaction is an intercompany hedging transaction with respect to O's risk A, the character and timing rules of § 1.1502-13 do not apply to the B-C transaction, and H's income, deduction, gain, or loss from C is ordinary. However, other attributes of the items from the B-C transaction are determined under § 1.1502-13. D is a hedging transaction with respect to C if it meets the requirements of paragraph (b) of this section.

(f) Identification and recordkeeping

(1) Same-day identification of hedging transactions. Under section 1221(a)(7), a taxpayer that enters into a hedging transaction (including recycling an existing hedging transaction) must clearly identify it as a hedging transaction before the close of the day on which the taxpayer acquired, originated, or entered into the transaction (or recycled the existing hedging transaction).

(2) Substantially contemporaneous identification of hedged item

(i) Content of the identification. A taxpayer that enters into a hedging transaction must identify the item, items, or aggregate risk being hedged. Identification of an item being hedged generally involves identifying a transaction that creates risk, and the type of risk that the transaction creates. For example, if a taxpayer is hedging the price risk with respect to its June purchases of corn inventory, the transaction being hedged is the June purchase of corn and the risk is price movements in the market where the taxpayer buys its corn. For additional rules concerning the content of this identification, see paragraph (f)(3) of this section.

(ii) Timing of the identification. The identification required by this paragraph (f)(2) must be made substantially contemporaneously with entering into the hedging transaction. An identification is not substantially contemporaneous if it is made more than 35 days after entering into the hedging transaction.

(3) Identification requirements for certain hedging transactions. In the case of the hedging transactions described in this paragraph (f)(3), the identification under paragraph (f)(2) of this section must include the information specified.

(i) Anticipatory asset hedges. If the hedging transaction relates to the anticipated acquisition of assets by the taxpayer, the identification must include the expected date or dates of acquisition and the amounts expected to be acquired.

(ii) Inventory hedges. If the hedging transaction relates to the purchase or sale of inventory by the taxpayer, the identification is made by specifying the type or class of inventory to which the transaction relates. If the hedging transaction relates to specific purchases or sales, the identification must also include the expected dates of the purchases or sales and the amounts to be purchased or sold.

(iii) Hedges of debt of the taxpayer

(A) Existing debt. If the hedging transaction relates to accruals or payments under an issue of existing debt of the taxpayer, the identification must specify the issue and, if the hedge is for less than the full issue price or the full term of the debt, the amount of the issue price and the term covered by the hedge.

(B) Debt to be issued. If the hedging transaction relates to the expected issuance of debt by the taxpayer or to accruals or payments under debt that is expected to be issued by the taxpayer, the identification must specify the following information: the expected date of issuance of the debt; the expected maturity or maturities; the total expected issue price; and the expected interest provisions. If the hedge is for less than the entire expected issue price of the debt or the full expected term of the debt, the identification must also include the amount or the term being hedged. The identification may indicate a range of dates, terms, and amounts, rather than specific dates, terms, or amounts. For example, a taxpayer might identify a transaction as hedging the yield on an anticipated issuance of fixed rate debt during the second half of its fiscal year, with the anticipated amount of the debt between $75 million and $125 million, and an anticipated term of approximately 20 to 30 years.

(iv) Hedges of aggregate risk

(A) Required identification. If a transaction hedges aggregate risk as described in paragraph (c)(3) of this section, the identification under paragraph (f)(2) of this section must include a description of the risk being hedged and of the hedging program under which the hedging transaction was entered. This requirement may be met by placing in the taxpayer's records a description of the hedging program and by establishing a system under which individual transactions can be identified as being entered into pursuant to the program.

(B) Description of hedging program. A description of a hedging program must include an identification of the type of risk being hedged, a description of the type of items giving rise to the risk being aggregated, and sufficient additional information to demonstrate that the program is designed to reduce aggregate risk of the type identified. If the program contains controls on speculation (for example, position limits), the description of the hedging program must also explain how the controls are established, communicated, and implemented.

(v) Transactions that counteract hedging transactions. If the hedging transaction is described in paragraph (d)(3) of this section, the description of the hedging transaction must include an identification of the risk management transaction that is being offset and the original underlying hedged item.

(4) Manner of identification and records to be retained

(i) Inclusion of identification in tax records. The identification required by this paragraph (f) must be made on, and retained as part of, the taxpayer's books and records.

(ii) Presence of identification must be unambiguous. The presence of an identification for purposes of this paragraph (f) must be unambiguous. The identification of a hedging transaction for financial accounting or regulatory purposes does not satisfy this requirement unless the taxpayer's books and records indicate that the identification is also being made for tax purposes. The taxpayer may indicate that individual hedging transactions, or a class or classes of hedging transactions, that are identified for financial accounting or regulatory purposes are also being identified as hedging transactions for purposes of this section.

(iii) Manner of identification. The taxpayer may separately and explicitly make each identification, or, so long as paragraph (f)(4)(ii) of this section is satisfied, the taxpayer may establish a system pursuant to which the identification is indicated by the type of transaction or by the manner in which the transaction is consummated or recorded. An identification under this system is made at the later of the time that the system is established or the time that the transaction satisfies the terms of the system by being entered, or by being consummated or recorded, in the designated fashion.

(iv) Principles of paragraph (f)(4)(iii) of this section illustrated. Paragraphs (f)(4)(iv)(A) through (C) of this section illustrate the principles of paragraph (f)(4)(iii) of this section and assume that the other requirements of this paragraph (f) are satisfied.

(A) A taxpayer can make an identification by designating a hedging transaction for (or placing it in) an account that has been identified as containing only hedges of a specified item (or of specified items or specified aggregate risk).

(B) A taxpayer can make an identification by including and retaining in its books and records a statement that designates all future transactions in a specified derivative product as hedges of a specified item, items, or aggregate risk.

(C) A taxpayer can make an identification by designating a certain mark, a certain form, or a certain legend as meaning that a transaction is a hedge of a specified item (or of specified items or a specified aggregate risk). Identification can be made by placing the designated mark on a record of the transaction (for example, trading ticket, purchase order, or trade confirmation) or by using the designated form or a record that contains the designated legend.

(5) Identification of hedges involving members of the same consolidated group

(i) General rule: single-entity approach. A member of a consolidated group must satisfy the requirements of this paragraph (f) as if all of the members of the group were divisions of a single corporation. Thus, the member entering into the hedging transaction with a third party must identify the hedging transaction under paragraph (f)(1) of this section. Under paragraph (f)(2) of this section, that member must also identify the item, items, or aggregate risk that is being hedged, even if the item, items, or aggregate risk relates primarily or entirely to other members of the group. If the members of a group use intercompany transactions to transfer risk within the group, the requirements of paragraph (f)(2) of this section may be met by identifying the intercompany transactions, and the risks hedged by the intercompany transactions, as hedges or hedged items, as appropriate. Because identification of the intercompany transaction as a hedge serves solely to identify the hedged item, the identification is timely if made within the period required by paragraph (f)(2) of this section. For example, if a member transfers risk in an intercompany transaction, it may identify under the rules of this paragraph (f) both its position in that transaction and the item, items, or aggregate risk being hedged. The member that hedges the risk outside the group may identify under the rules of this paragraph (f) both its position with the third party and its position in the intercompany transaction. Paragraph (e)(4) Example 1 of this section illustrates this identification.

(ii) Rule for consolidated groups making the separate-entity election. If a consolidated group makes the separate-entity election under paragraph (e)(2) of this section, each member of the group must satisfy the requirements of this paragraph (f) as though it were not a member of a consolidated group.

(6) Consistency with section 1256(e)(2). Any identification for purposes of section 1256(e)(2) is also an identification for purposes of paragraph (f)(1) of this section.

(g) Effect of identification and non-identification

(1) Transactions identified

(i) In general. If a taxpayer identifies a transaction as a hedging transaction for purposes of paragraph (f)(1) of this section, the identification is binding with respect to gain, whether or not all of the requirements of paragraph (f) of this section are satisfied. Thus, gain from that transaction is ordinary income. If the transaction is not in fact a hedging transaction described in paragraph (b) of this section, however, paragraphs (a)(1) and (2) of this section do not apply and the character of loss is determined without reference to whether the transaction is a surrogate for a noncapital asset, serves as insurance against a business risk, serves a hedging function, or serves a similar function or purpose. Thus, the taxpayer's identification of the transaction as a hedging transaction does not itself make loss from the transaction ordinary.

(ii) Inadvertent identification. Notwithstanding paragraph (g)(1)(i) of this section, if the taxpayer identifies a transaction as a hedging transaction for purposes of paragraph (f) of this section, the character of the gain is determined as if the transaction had not been identified as a hedging transaction if—

(A) The transaction is not a hedging transaction (as defined in paragraph (b) of this section);

(B) The identification of the transaction as a hedging transaction was due to inadvertent error; and

(C) All of the taxpayer's transactions in all open years are being treated on either original or, if necessary, amended returns in a manner consistent with the principles of this section.

(2) Transactions not identified

(i) In general. Except as provided in paragraphs (g)(2)(ii) and (iii) of this section, the absence of an identification that satisfies the requirements of paragraph (f)(1) of this section is binding and establishes that a transaction is not a hedging transaction. Thus, subject to the exceptions, the rules of paragraphs (a)(1) and (2) of this section do not apply, and the character of gain or loss is determined without reference to whether the transaction is a surrogate for a noncapital asset, serves as insurance against a business risk, serves a hedging function, or serves a similar function or purpose.

(ii) Inadvertent error. If a taxpayer does not make an identification that satisfies the requirements of paragraph (f) of this section, the taxpayer may treat gain or loss from the transaction as ordinary income or loss under paragraph (a)(1) or (2) of this section if—

(A) The transaction is a hedging transaction (as defined in paragraph (b) of this section);

(B) The failure to identify the transaction was due to inadvertent error; and

(C) All of the taxpayer's hedging transactions in all open years are being treated on either original or, if necessary, amended returns as provided in paragraphs (a)(1) and (2) of this section.

(iii) Anti-abuse rule. If a taxpayer does not make an identification that satisfies all the requirements of paragraph (f) of this section but the taxpayer has no reasonable grounds for treating the transaction as other than a hedging transaction, then gain from the transaction is ordinary. The reasonableness of the taxpayer's failure to identify a transaction is determined by taking into consideration not only the requirements of paragraph (b) of this section but also the taxpayer's treatment of the transaction for financial accounting or other purposes and the taxpayer's identification of similar transactions as hedging transactions.

(3) Transactions by members of a consolidated group

(i) Single-entity approach. If a consolidated group is under the general rule of paragraph (e)(1) of this section (the single-entity approach), the rules of this paragraph (g) apply only to transactions that are not intercompany transactions.

(ii) Separate-entity election. If a consolidated group has made the election under paragraph (e)(2) of this section, then, in addition to the rules of paragraphs (g)(1) and (2) of this section, the following rules apply:

(A) If an intercompany transaction is identified as a hedging transaction but does not meet the requirements of paragraphs (e)(2)(ii)(A) and (B) of this section, then, notwithstanding any contrary provision in § 1.1502-13, each party to the transaction is subject to the rules of paragraph (g)(1) of this section with respect to the transaction as though it had incorrectly identified its position in the transaction as a hedging transaction.

(B) If a transaction meets the requirements of paragraphs (e)(2)(ii) (A) and (B) of this section but the transaction is not identified as a hedging transaction, each party to the transaction is subject to the rules of paragraph (g)(2) of this section. (Because the transaction is an intercompany hedging transaction, the character and timing rules of § 1.1502-13 do not apply. See paragraph (e)(2)(iii)(A) of this section.)

(h) Effective date. The rules of this section apply to transactions entered into on or after March 20, 2002.

(i) [Reserved]. For further guidance, see § 1.1221-2T(i) through (j)(1).

(j) Effective/applicability date. Paragraph (e)(2)(iv) of this section applies to any original consolidated Federal income tax return due (without extensions) after June 14, 2007. For original consolidated Federal income tax returns due (without extensions) after May 30, 2006, and on or before June 14, 2007, see § 1.1221-2T as contained in 26 CFR part 1 in effect on April 1, 2007. For original consolidated Federal income tax returns due (without extensions) on or before May 30, 2006, see § 1.1221-2 as contained in 26 CFR part 1 in effect on April 1, 2006.

[T.D. 8985, 67 FR 12865, Mar. 20, 2002, as amended by T.D. 9264, 71 FR 30602, May 30, 2006; T.D. 9329, 72 FR 32804, June 14, 2007]

§ 1.1221-3 Time and manner for electing capital asset treatment for certain self-created musical works.

(a) Description. Section 1221(b)(3) allows an electing taxpayer to treat the sale or exchange of a musical composition or a copyright in a musical work created by the taxpayer's personal efforts (or having a basis determined by reference to the basis of such property in the hands of a taxpayer whose personal efforts created such property) as the sale or exchange of a capital asset. As a consequence, gain or loss from the sale or exchange is treated as capital gain or loss.

(b) Time and manner for making the election. An election described in this section is made separately for each musical composition (or copyright in a musical work) sold or exchanged during the taxable year. An election must be made on or before the due date (including extensions) of the income tax return for the taxable year of the sale or exchange. The election is made on Schedule D, “Capital Gains and Losses,” of the appropriate income tax form (for example, Form 1040, “U.S. Individual Income Tax Return;” Form 1065, “U.S. Return of Partnership Income;” Form 1120, “U.S. Corporation Income Tax Return”) by treating the sale or exchange as the sale or exchange of a capital asset, in accordance with the form and its instructions.

(c) Revocability of election. The election described in this section is revocable with the consent of the Commissioner. To seek consent to revoke the election, a taxpayer must submit a request for a letter ruling under the applicable administrative procedures. Alternatively, an automatic extension of 6 months from the due date of the taxpayer's income tax return (excluding extensions) is granted to revoke the election, provided the taxpayer timely filed the taxpayer's income tax return and, within this 6-month extension period, the taxpayer files an amended income tax return that treats the sale or exchange as the sale or exchange of property that is not a capital asset.

(d) Effective/applicability date. This section applies to elections under section 1221(b)(3) in taxable years beginning after May 17, 2006.

[T.D. 9514, 76 FR 6554, Feb. 7, 2011]

§ 1.1222-1 Other terms relating to capital gains and losses.

(a) The phrase short-term applies to the category of gains and losses arising from the sale or exchange of capital assets held for 1 year (6 months for taxable years beginning before 1977; 9 months for taxable years beginning in 1977) or less; the phrase long-term to the category of gains and losses arising from the sale or exchange of capital assets held for more than 1 year (6 months for taxable years beginning before 1977; 9 months for taxable years beginning in 1977). The fact that some part of a loss from the sale or exchange of a capital asset may be finally disallowed because of the operation of section 1211 does not mean that such loss is not taken into account in computing taxable income within the meaning of that phrase as used in sections 1222(2) and 1222(4).

(b)

(1) In the definition of net short-term capital gain, as provided in section 1222(5), the amounts brought forward to the taxable year under section 1212 (other than section 1212(b)(1)(B)) are short-term capital losses for such taxable year.

(2) In the definition of net long-term capital gain, as provided in section 1222(7), the amounts brought forward to the taxable year under section 1212(b)(1)(B) are long-term capital losses for such taxable year.

(c) Gains and losses from the sale or exchange of capital assets held for not more than 1 year (6 months for taxable years beginning before 1977; 9 months for taxable years beginning in 1977) (described as short-term capital gains and short-term capital losses) shall be segregated from gains and losses arising from the sale or exchange of such assets held for more than 1 year (6 months for taxable years beginning before 1977; 9 months for taxable years beginning in 1977) (described as long-term capital gains and long-term capital losses).

(d)

(1) The term capital gain net income (net capital gain for taxable years beginning before January 1, 1977) means the excess of the gains from sales or exchanges of capital assets over the losses from sales or exchanges of capital assets, which losses include any amounts carried to the taxable year pursuant to section 1212(a) or section 1212(b).

(2) Notwithstanding subparagraph (1) of this paragraph, in the case of a taxpayer other than a corporation for taxable years beginning before January 1, 1964, the term net capital gain means the excess of

(i) the sum of the gains from sales or exchanges of capital assets, plus the taxable income (computed without regard to gains and losses from sales or exchanges of capital assets and without regard to the deductions provided by section 151, relating to personal exemptions, or any deductions in lieu thereof) of the taxpayer or $1,000, whichever is smaller, over

(ii) the losses from sales or exchanges of capital assets, which losses include amounts carried to the taxable year by such taxpayer under paragraph (a)(1) of § 1.1212-1. Thus, in the case of estates and trusts for taxable years beginning before January 1, 1964, taxable income for the purposes of this paragraph shall be computed without regard to gains and losses from sales or exchanges of capital assets and without regard to the deductions allowed by section 642(b) to estates and trusts in lieu of personal exemptions. The term net capital gain is not applicable in the case of a taxpayer other than a corporation for taxable years beginning after December 31, 1963, and before January 1, 1970. In the case of a taxpayer whose tax liability is computed under section 3 for taxable years beginning before January 1, 1964, the term taxable income, for purposes of this paragraph, shall be read as adjusted gross income.

(e) The term net capital loss means the excess of the losses from sales or exchanges of capital assets over the sum allowed under section 1211. However, in the case of a corporation, amounts which are short-term capital losses under § 1.1212-1(a) are excluded in determining such net capital loss.

(f) See section 165(g) and section 166(e), under which losses from worthless stocks, bonds, and other securities (if they constitute capital assets) are required to be treated as losses under subchapter P (section 1201 and following), chapter 1 of the Code, from the sale or exchange of capital assets, even though such securities are not actually sold or exchanged. See also section 1231 and § 1.1231-1 for the determination of whether or not gains and losses from the involuntary conversion of capital assets and from the sale, exchange, or involuntary conversion of certain property used in the trade or business shall be treated as gains and losses from the sale or exchange of capital assets. See also section 1236 and § 1.1236-1 for the determination of whether or not gains from the sale or exchange of securities by a dealer in securities shall be treated as capital gains, or whether losses from such sales or exchanges shall be treated as ordinary losses.

(g) In the case of nonresident alien individuals not engaged in trade or business within the United States, see section 871 and the regulations thereunder for the determination of the net amount of capital gains subject to tax.

(h) The term net capital gain (net section 1201 gain for taxable years beginning before January 1, 1977) means the excess of the net long-term capital gain for the taxable year over the net short-term capital loss for such year.

[T.D. 6500, 25 FR 12004, Nov. 26, 1960, as amended by T.D. 6828, 30 FR 7808, June 17, 1965; T.D. 6867, 30 FR 15096, Dec. 7, 1965; T.D. 7301, 39 FR 971, Jan. 4, 1974; T.D. 7337, 39 FR 44978, Dec. 30, 1974; T.D. 7728, 45 FR 72650, Nov. 3, 1980]

§ 1.1223-1 Determination of period for which capital assets are held.

(a) The holding period of property received in an exchange by a taxpayer includes the period for which the property which he exchanged was held by him, if the property received has the same basis in whole or in part for determining gain or loss in the hands of the taxpayer as the property exchanged. However, this rule shall apply, in the case of exchanges after March 1, 1954, only if the property exchanged was at the time of the exchange a capital asset in the hands of the taxpayer or property used in his trade or business as defined in section 1231(b). For the purposes of this paragraph, the term exchange includes the following transactions:

(1) An involuntary conversion described in section 1033, and

(2) A distribution to which section 355 (or so much of section 356 as relates to section 355) applies.

Thus, if property acquired as the result of a compulsory or involuntary conversion of other property of the taxpayer has under section 1033(c) the same basis in whole or in part in the hands of the taxpayer as the property so converted, its acquisition is treated as an exchange and the holding period of the newly acquired property shall include the period during which the converted property was held by the taxpayer. Thus, also, where stock of a controlled corporation is received by a taxpayer pursuant to a distribution to which section 355 (or so much of section 356 as relates to section 355) applies, the distribution is treated as an exchange and the period for which the taxpayer has held the stock of the controlled corporation shall include the period for which he held the stock of the distributing corporation with respect to which such distribution was made.

(b) The holding period of property in the hands of a taxpayer shall include the period during which the property was held by any other person, if such property has the same basis in whole or in part in the hands of the taxpayer for determining gain or loss from a sale or exchange as it would have in the hands of such other person. For example, the period for which property acquired by gift after December 31, 1920, was held by the donor must be included in determining the period for which the property was held by the taxpayer if, under the provisions of section 1015, such property has, for the purpose of determining gain or loss from the sale or exchange, the same basis in the hands of the taxpayer as it would have in the hands of the donor. Similarly, the period for which property acquired from a decedent who died in 2010 was held by the decedent must be included in determining the period during which the property was held by the recipient, if the recipient's basis in the property is determined under section 1022.

(c) In determining the period for which the taxpayer has held stock or securities received upon a distribution where no gain was recognized to the distributee under section 1081(c) (or under section 112(g) of the Revenue Act of 1928 (45 Stat. 818) or the Revenue Act of 1932 (47 Stat. 197)), there shall be included the period for which he held the stock or securities in the distributing corporation before the receipt of the stock or securities on such distribution.

(d) If the acquisition of stock or securities resulted in the nondeductibility (under section 1091, relating to wash sales) of the loss from the sale or other disposition of substantially identical stock or securities, the holding period of the newly acquired securities shall include the period for which the taxpayer held the securities with respect to which the loss was not allowable.

(e) The period for which the taxpayer has held stock, or stock subscription rights, received on a distribution shall be determined as though the stock dividend, or stock right, as the case may be, were the stock in respect of which the dividend was issued if the basis for determining gain or loss upon the sale or other disposition of such stock dividend or stock right is determined under section 307. If the basis of stock received by a taxpayer pursuant to a spin-off is determined under so much of section 1052(c) as refers to section 113(a)(23) of the Internal Revenue Code of 1939, and such stock is sold or otherwise disposed of in a taxable year which is subject to the Internal Revenue Code of 1954, the period for which the taxpayer has held the stock received in such spin-off shall include the period for which he held the stock of the distributing corporation with respect to which such distribution was made.

(f) The period for which the taxpayer has held stock or securities issued to him by a corporation pursuant to the exercise by him of rights to acquire such stock or securities from the corporation will, in every case and whether or not the receipt of taxable gain was recognized in connection with the distribution of the rights, begin with and include the day upon which the rights to acquire such stock or securities were exercised. A taxpayer will be deemed to have exercised rights received from a corporation to acquire stock or securities therein where there is an expression of assent to the terms of such rights made by the taxpayer in the manner requested or authorized by the corporation.

(g) The period for which the taxpayer has held a residence, the acquisition of which resulted under the provisions of section 1034 in the nonrecognition of any part of the gain realized on the sale or exchange of another residence, shall include the period for which such other residence had been held as of the date of such sale or exchange. For purposes of this paragraph, the term sale or exchange includes an involuntary conversion occurring after December 31, 1950, and before January 1, 1954.

(h) If a taxpayer accepts delivery of a commodity in satisfaction of a commodity futures contract, the holding period of the commodity shall include the period for which the taxpayer held the commodity futures contract, if such futures contract was a capital asset in his hands.

(i) If shares of stock in a corporation are sold from lots purchased at different dates or at different prices and the identity of the lots cannot be determined, the rules prescribed by the regulations under section 1012 for determining the cost or other basis of such stocks so sold or transferred shall also apply for the purpose of determining the holding period of such stock.

(j) In the case of a person acquiring property, or to whom property passed, from a decedent (within the meaning of section 1014(b)) dying after December 31, 1970, such person shall be considered to have held the property for more than 1 year (6 months for taxable years beginning before 1977; 9 months for taxable years beginning in 1977) if the property:

(1) Has a basis in the hands of such person which is determined in whole or in part under section 1014, and

(2) Is sold or otherwise disposed of by such person within 6 months after the decedent's death.

The provisions of this paragraph apply to sales of such property included in the decedent's gross estate for the purposes of the estate tax by the executor or administrator of the estate and to sales of such property by other persons who have acquired property from the decedent. The provisions of this paragraph may also be applicable to cases involving joint tenancies, community property, and properties transferred in contemplation of death. Thus, if a surviving joint tenant, who acquired property by right of survivorship, sells or otherwise disposes of such property within 6 months after the date of the decedent's death, and the basis of the property in his hands is determined in whole or in part under section 1014, the property shall be considered to have been held by the surviving joint tenant for more than 6 months. Similarly, a surviving spouse's share of community property shall be considered to have been held by her for more than 6 months if it is sold or otherwise disposed of within 6 months after the date of the decedent's death, regardless of when the property was actually acquired by the marital community. For the purposes of this paragraph, it is immaterial that the sale or other disposition produces gain or loss. If property is considered to have been held for more than 6 months by reason of this paragraph, it also is considered to have been held for that period for purposes of section 1231 (if that section is otherwise applicable).

(k) Any reference in section 1223 or this section to another provision of the Internal Revenue Code of 1954 is, where applicable, to be deemed a reference to the corresponding provision of the Internal Revenue Code of 1939, or prior internal revenue laws. The provisions of prior internal revenue laws here intended are the sections referred to in the sections of the Internal Revenue Code of 1939 which correspond to the sections of the Internal Revenue Code of 1954 referred to in section 1223. Thus, the sections corresponding to section 1081(c) are section 371(c) of the Revenue Act of 1938 (52 Stat. 553) and section 371(c) of the Internal Revenue Code of 1939. The sections corresponding to section 1091 are section 118 of each of the following: The Revenue Acts of 1928 (45 Stat. 826), 1932 (47 Stat. 208), 1934 (48 Stat. 715), 1936 (49 Stat. 1692), 1938 (52 Stat. 503), and the Internal Revenue Code of 1939.

(l) Effective/applicability date. This section applies January 19, 2017. For rules before January 19, 2017, see § 1.1223-1 as contained in 26 CFR part 1 revised as of April 1, 2016.

[T.D. 6500, 25 FR 12005, Nov. 26, 1960, as amended by T.D. 7238, 37 FR 28717, Dec. 29, 1972; T.D. 7728, 45 FR 72650, Nov. 3, 1980; T.D. 9811, 82 FR 6241, Jan. 19, 2017; T.D. 9849, 84 FR 9237, Mar. 14, 2019]

§ 1.1223-3 Rules relating to the holding periods of partnership interests.

(a) In general. A partner shall not have a divided holding period in an interest in a partnership unless—

(1) The partner acquired portions of an interest at different times; or

(2) The partner acquired portions of the partnership interest in exchange for property transferred at the same time but resulting in different holding periods (e.g., section 1223).

(b) Accounting for holding periods of an interest in a partnership

(1) General rule. The portion of a partnership interest to which a holding period relates shall be determined by reference to a fraction, the numerator of which is the fair market value of the portion of the partnership interest received in the transaction to which the holding period relates, and the denominator of which is the fair market value of the entire partnership interest (determined immediately after the transaction).

(2) Special rule. For purposes of applying paragraph (b)(1) of this section to determine the holding period of a partnership interest (or portion thereof) that is sold or exchanged (or with respect to which gain or loss is recognized upon a distribution under section 731), if a partner makes one or more contributions of cash to the partnership and receives one or more distributions of cash from the partnership during the one-year period ending on the date of the sale or exchange (or distribution with respect to which gain or loss is recognized under section 731), the partner may reduce the cash contributions made during the year by cash distributions received on a last-in-first-out basis, treating all cash distributions as if they were received immediately before the sale or exchange (or at the time of the distribution with respect to which gain or loss is recognized under section 731).

(3) Deemed contributions and distributions. For purposes of paragraphs (b)(1) and (2) of this section, deemed contributions of cash under section 752(a) and deemed distributions of cash under section 752(b) shall be disregarded to the same extent that such amounts are disregarded under § 1.704-1(b)(2)(iv)(c).

(4) Adjustment with respect to contributed section 751 assets. For purposes of applying paragraph (b)(1) of this section to determine the holding period of a partnership interest (or portion thereof) that is sold or exchanged, if a partner receives a portion of the partnership interest in exchange for property described in section 751(c) or (d) (section 751 assets) within the one-year period ending on the date of the sale or exchange of all or a portion of the partner's interest in the partnership, and the partner recognizes ordinary income or loss on account of such a section 751 asset in a fully taxable transaction (either as a result of the sale of all or part of the partner's interest in the partnership or the sale by the partnership of the section 751 asset), the contribution of the section 751 asset during the one-year period shall be disregarded. However, if, in the absence of this paragraph, a partner would not be treated as having held any portion of the interest for more than one year (e.g., because the partner's only contributions to the partnership are contributions of section 751 assets or section 751 assets and cash within the prior one-year period), this adjustment is not available.

(5) Divided holding period if partnership interest comprises in whole or in part one or more profits interests

(i) In general. If a partnership interest is comprised in whole or in part of one or more profits interests (as defined in paragraph (b)(5)(ii) of this section), then, for purposes of applying paragraph (b)(1) of this section, the portion of the holding period to which a profits interest relates is determined based on the fair market value of the profits interest upon the disposition of all, or part, of the interest (and not at the time that the profits interest is acquired). Paragraph (b)(1) of this section continues to apply to the extent that a partner acquires portions of a partnership interest that are not comprised of a profits interest and the value of the profits interest is not included for purposes of determining the value of the entire partnership interest under paragraph (b)(1).

(ii) Definition of capital interest and profits interest. For purposes of this paragraph (b)(5), a profits interest is a partnership interest other than a capital interest. A capital interest is an interest that would give the holder a share of the proceeds if the partnership's assets were sold at fair market value at the time the interest was received and then the proceeds were distributed in a complete liquidation of the partnership. A profits interest, for purposes of this paragraph (b)(5), is received in connection with the performance of services to or for the benefit of a partnership in a partner capacity or in anticipation of being a partner, and the receipt of the interest is not treated as a taxable event for the partner or the partnership under applicable Federal income tax guidance.

(6) Exception. The Commissioner may prescribe by guidance published in the Internal Revenue Bulletin (see § 601.601(d)(2) of this chapter) a rule disregarding certain cash contributions (including contributions of a de minimis amount of cash) in applying paragraph (b)(1) of this section to determine the holding period of a partnership interest (or portion thereof) that is sold or exchanged.

(c) Sale or exchange of all or a portion of an interest in a partnership

(1) Sale or exchange of entire interest in a partnership. If a partner sells or exchanges the partner's entire interest in a partnership, any capital gain or loss recognized shall be divided between long-term and short-term capital gain or loss in the same proportions as the holding period of the interest in the partnership is divided between the portion of the interest held for more than one year and the portion of the interest held for one year or less.

(2) Sale or exchange of a portion of an interest in a partnership

(i) Certain publicly traded partnerships. A selling partner in a publicly traded partnership (as defined under section 7704(b)) may use the actual holding period of the portion of a partnership interest transferred if—

(A) The ownership interest is divided into identifiable units with ascertainable holding periods;

(B) The selling partner can identify the portion of the partnership interest transferred; and

(C) The selling partner elects to use the identification method for all sales or exchanges of interests in the partnership after September 21, 2000. The selling partner makes the election referred to in this paragraph (c)(2)(i)(C) by using the actual holding period of the portion of the partner's interest in the partnership first transferred after September 21, 2000 in reporting the transaction for Federal income tax purposes.

(ii) Other partnerships. If a partner has a divided holding period in a partnership interest, and paragraph (c)(2)(i) of this section does not apply, then the holding period of the transferred interest shall be divided between long-term and short-term capital gain or loss in the same proportions as the long-term and short-term capital gain or loss that the transferor partner would realize if the entire interest in the partnership were transferred in a fully taxable transaction immediately before the actual transfer.

(d) Distributions

(1) In general. Except as provided in paragraph (b)(2) of this section, a partner's holding period in a partnership interest is not affected by distributions from the partnership.

(2) Character of capital gain or loss recognized as a result of a distribution from a partnership. If a partner is required to recognize capital gain or loss as a result of a distribution from a partnership, then the capital gain or loss recognized shall be divided between long-term and short-term capital gain or loss in the same proportions as the long-term and short-term capital gain or loss that the distributee partner would realize if such partner's entire interest in the partnership were transferred in a fully taxable transaction immediately before the distribution.

(e) Section 751(c) assets. For purposes of this section, properties and potential gain treated as unrealized receivables under section 751(c) shall be treated as separate assets that are not capital assets as defined in section 1221 or property described in section 1231.

(f) Examples. The provisions of this section are illustrated by the following examples:

(1) Example 1. Division of holding period—contribution of money and a capital asset.

(i) A contributes $5,000 of cash and a nondepreciable capital asset A has held for two years to a partnership (PRS) for a 50 percent interest in PRS. A's basis in the capital asset is $5,000, and the fair market value of the asset is $10,000. After the exchange, A's basis in A's interest in PRS is $10,000, and the fair market value of the interest is $15,000. A received one-third of the interest in PRS for a cash payment of $5,000 ($5,000/$15,000). Therefore, A's holding period in one-third of the interest received (attributable to the contribution of money to the partnership) begins on the day after the contribution. A received two-thirds of the interest in PRS in exchange for the capital asset ($10,000/$15,000). Accordingly, pursuant to section 1223(1), A has a two-year holding period in two-thirds of the interest received in PRS.

(ii) Six months later, when A's basis in PRS is $12,000 (due to a $2,000 allocation of partnership income to A), A sells the interest in PRS for $17,000. Assuming PRS holds no inventory or unrealized receivables (as defined under section 751(c)) and no collectibles or section 1250 property, A will realize $5,000 of capital gain. As determined above, one-third of A's interest in PRS has a holding period of one year or less, and two-thirds of A's interest in PRS has a holding period equal to two years and six months. Therefore, one-third of the capital gain will be short-term capital gain, and two-thirds of the capital gain will be long-term capital gain.

(2) Example 2. Division of holding period—contribution of section 751 asset and a capital asset.

A contributes inventory with a basis of $2,000 and a fair market value of $6,000 and a capital asset which A has held for more than one year with a basis of $4,000 and a fair market value of $6,000, and B contributes cash of $12,000 to form a partnership (AB). As a result of the contribution, one-half of A's interest in AB is treated as having been held for more than one year under section 1223(1). Six months later, A transfers one-half of A's interest in AB to C for $6,000, realizing a gain of $3,000. If AB were to sell all of its section 751 property in a fully taxable transaction immediately before A's transfer of the partnership interest, A would be allocated $4,000 of ordinary income on account of the inventory. Accordingly, A will recognize $2,000 of ordinary income and $1,000 of capital gain ($3,000-$2,000) on account of the transfer to C. Because A recognizes ordinary income on account of the inventory that was contributed to AB within the one year period ending on the date of the sale, the inventory will be disregarded in determining the holding period of A's interest in AB. All of the capital gain will be long-term.

(3) Example 3. Netting of cash contributions and distributions.

(i) On January 1, 2000, A holds a 50 percent interest in the capital and profits of a partnership (PS). The value of A's PS interest is $900, and A's holding period in the entire interest is long-term. On January 2, 2000, when the value of A's PS interest is still $900, A contributes $100 to PS. On June 1, 2000, A receives a distribution of $40 cash from the partnership. On September 1, 2000, when the value of A's interest in PS is $1,350, A contributes an additional $230 cash to PS, and on October 1, 2000, A receives another $40 cash distribution from PS. A sells A's entire partnership interest on November 1, 2000, for $1,600. A's adjusted basis in the PS interest at the time of the sale is $1,000.

(ii) For purposes of netting cash contributions and distributions in determining the holding period of A's interest in PS, A is treated as having received a distribution of $80 on November 1, 2000. Applying that distribution on a last-in-first-out basis to reduce prior contributions during the year, the contribution made on September 1, 2000, is reduced to $150 ($230-$80). The holding period then is determined as follows: Immediately after the contribution of $100 on January 2, 2000, A's holding period in A's PS interest is 90 percent long-term ($900/($900 + $100)) and 10 percent short-term ($100/($900 + $100)). The contribution of $150 on September 1, 2000, causes 10 percent of A's partnership interest ($150/($1,350 + $150)) to have a short-term holding period. Accordingly, immediately after the contribution on September 1, 2000, A's holding period in A's PS interest is 81 percent long-term (.90 × .90) and 19 percent short-term ((.10 × .90) + .10). Accordingly, $486 ($600 × .81) of the gain from A's sale of the PS interest is long-term capital gain, and $114 ($600 × .19) is short-term capital gain.

(4) Example 4. Division of holding period when capital account is increased by contribution.

A, B, C, and D are equal partners in a partnership (PRS), and the fair market value of a 25 percent interest in PRS is $100. A, B, C, and D each contribute an additional $100 to partnership capital, thereby increasing the fair market value of each partner's interest to $200. As a result of the contribution, each partner has a new holding period in the portion of the partner's interest in PRS that is attributable to the contribution. That portion equals 50 percent ($100/$200) of each partner's interest in PRS.

(5) Example 5. Sale or exchange of a portion of an interest in a partnership.

(i) A, B, and C form an equal partnership (PRS). In connection with the formation, A contributes $5,000 in cash and a capital asset (capital asset 1) with a fair market value of $5,000 and a basis of $2,000; B contributes $7,000 in cash and a capital asset (capital asset 2) with a fair market value of $3,000 and a basis of $3,000; and C contributes $10,000 in cash. At the time of the contribution, A had held the contributed property for two years. Six months later, when A's basis in PRS is $7,000, A transfers one-half of A's interest in PRS to T for $7,000 at a time when PRS's balance sheet (reflecting a cash receipts and disbursements method of accounting) is as follows:

ASSETS
Adjusted basis Market value
Cash $22,000 $22,000
Unrealized Receivables 0 6,000
Capital Asset 1 2,000 5,000 Capital Asset 2 3,000 9,000
Capital Assets 5,000 14,000
Total 27,000 42,000

(ii) Although at the time of the transfer A has not held A's interest in PRS for more than one year, 50 percent of the fair market value of A's interest in PRS was received in exchange for a capital asset with a long-term holding period. Therefore, 50 percent of A's interest in PRS has a long-term holding period.

(iii) If PRS were to sell all of its section 751 property in a fully taxable transaction immediately before A's transfer of the partnership interest, A would be allocated $2,000 of ordinary income. One-half of that amount ($1,000) is attributable to the portion of A's interest in PRS transferred to T. Accordingly, A will recognize $1,000 oridnary income and $2,500 ($3,500-$1,000) of capital gain on account of the transfer to T of one-half of A's interest in PRS. Fifty percent ($1,250) of that gain is long-term capital gain and 50 percent ($1,250) is short-term capital gain.

(6) Example 6. Sale of units of interests in a partnership.

A publicly traded partnership (PRS) has ownership interests that are segregated into identifiable units of interest. A owns 10 limited partnership units in PRS for which A paid $10,000 on January 1, 1999. On August 1, 2000, A purchases five additional units for $10,000. At the time of purchase, the fair market value of each unit has increased to $2,000. A's holding period for one-third ($10,000/$30,000) of the interest in PRS begins on the day after the purchase of the five additional units. Less than one year later, A sells five units of ownership in PRS for $11,000. At the time, A's basis in the 15 units of PRS is $20,000, and A's capital gain on the sale of 5 units is $4,333 (amount realized of $11,000−one-third of the adjusted basis or $6,667). For purposes of determining the holding period, A can designate the specific units of PRS sold. If A properly identifies the five units sold as five of the ten units for which A has a long-term holding period and elects to use the identification method for all subsequent sales or exchanges of interests in the partnership by using the actual holding period in reporting the transaction on A's Federal income tax return, the capital gain realized will be long-term capital gain.

(7) Example 7. Disproportionate distribution.

In 1997, A and B each contribute cash of $50,000 to form and become equal partners in a partnership (PRS). More than one year later, A receives a distribution worth $22,000 from PRS, which reduces A's interest in PRS to 36 percent. After the distribution, B owns 64 percent of PRS. The holding periods of A and B in their interests in PRS are not affected by the distribution.

(8) Example 8. Gain or loss as a result of a distribution.

(i) On January 1, 1996, A contributes property with a basis of $10 and a fair market value of $10,000 in exchange for an interest in a partnership (ABC). On September 30, 2000, when A's interest in ABC is worth $12,000 (and the basis of A's partnership interest is still $10), A contributes $12,000 cash in exchange for an additional interest in ABC. A is allocated a loss equal to $10,000 by ABC for the taxable year ending December 31, 2000, thereby reducing the basis of A's partnership interest to $2,010. On February 1, 2001, ABC makes a cash distribution to A of $10,000. ABC holds no inventory or unrealized receivables. (assume that A is allocated no gain or loss for the taxable year ending December 31, 2001, so that the basis of A's partnership interest does not increase or decrease as a result of such allocations.)

(ii) The netting rule contained in paragraph (b)(2) of this section provides that, in determining the holding period of A's interest in ABC, the cash contribution made on September 30, 2000, must be reduced by the distribution made on February 1, 2001. Accordingly, for purposes of determining the holding period of A's interest in ABC, A is treated as having made a cash contribution of $2,000 ($12,000-$10,000) to ABC on September 30, 2000. A's holding period in one-seventh of A's interest in ABC ($2,000 cash contributed over the $14,000 value of the entire interest (determined as if only $2,000 were contributed rather than $12,000)) begins on the day after the cash contribution. A recognizes $7,990 of capital gain as a result of the distribution. See section 731(a)(1). One-seventh of the capital gain recognized as a result of the distribution is short-term capital gain, and six-sevenths of the capital gain is long-term capital gain. After the distribution, A's basis in the interest in PRS is $0, and the holding period for the interest in PRS continues to be divided in the same proportions as before the distribution.

(9) Example 9. On June 1, 2020, GP contributes $10,000 to PRS for a partnership interest in PRS. On June 30, 2023, GP receives a 20% interest in the profits of PRS that is an Applicable Partnership Interest (API) as defined in § 1.1061-1(a). On June 30, 2025, GP sells its interest in PRS for $30,000. At the time of GP's sale of its interest, the API has a fair market value of $15,000. GP has a divided holding period in its interest in PRS; 50% of the partnership interest has a holding period beginning on June 1, 2020, and 50% has a holding period that begins on June 30, 2023.

(10) Example 10. Assume the same facts as in paragraph (f)(9) of this section (Example 9), except that on June 30, 2024, GP contributes an additional $5,000 cash to GP prior to GP's sale of its interest in 2025. Immediately after the contribution of the $5,000 on June 30, 2024, GP's interest in PRS has a value of $15,000, not taking into account the value of GP's profits interest in PRS. GP calculates its holding period in the portions not comprised by the profits interest and two-thirds of its holding period runs from June 1, 2020, and one-third runs from June 30, 2024. On June 30, 2025, GP sells its interest for $30,000 and the API has a fair market value of $15,000. Accordingly, on the date of disposition, one-third of GP's interest has a five year holding period from its interest received in 2020 for its $10,000 contribution, one-half of GP's interest has a two year holding period from the profits interest issued on June 30, 2023, and one-sixth of GP's interest has a one year holding period from the contribution of the $5,000.

(g) Applicability dates. This section applies to transfers of partnership interests and distributions of property from a partnership that occur on or after September 21, 2000. Paragraphs (b)(5) and (f)(9) and (10) of this section apply to taxable years beginning on or after January 19, 2021.

[T.D. 8902, 65 FR 57099, Sept. 21, 2000, as amended by T.D. 9945, 86 FR 5494, Jan. 19, 2021; T.D. 9945, 89 FR 50526, June 14, 2024]